Get Paid Early: Cash Advance
StreamFunds, Inc.FinanceVerified
- 167.00 Reviews
- 4.2
- Downloads
- 50,000+
- Price
- Free
Screenshots
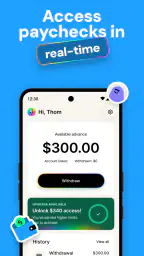
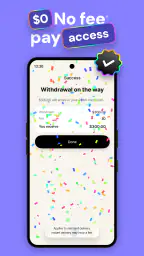
 Analysis by Appwesome
When a payday feels too far away, a small timing gap can become surprisingly stressful. Get Paid Early: Cash Advance is a finance app from StreamFunds, Inc. built around that exact problem: helping eligible users access earned pay before the normal payday, without presenting the service as a traditional loan. I found the idea easy to understand, but the important distinction is that early access is useful only when the money is already earned and the repayment or payroll timing fits your situation.
The app is free to install and carries an Everyone age rating, which makes it approachable for a broad audience. It has reached over fifty thousand installs and holds a 4.2 average from around seven hundred ratings, so there is enough public activity to suggest that people are using it for real cash-flow needs rather than treating it as a novelty. The current release is version 3.0.39, and it requires Android 7.0 or later.
What to expect before requesting early pay
The first thing I would tell a new user is not to think of this as a replacement for budgeting, savings, or regular income. Its purpose is narrower and more practical: bridge the distance between work already completed and the date when that pay normally arrives. That makes it potentially helpful for an urgent grocery run, a transport cost, or a bill that lands just before payday. It is less suitable for repeated spending that leaves every future paycheck short.
The store summary emphasizes no loans, no interest, and no hidden fees. That is an important reason to look at this service instead of immediately turning to a conventional payday lender or credit card cash advance. Still, “no interest” does not mean every part of the experience will feel frictionless. Eligibility, employer or payroll connection, identity checks, timing, and the amount available can all affect whether the app solves your problem quickly.
I also appreciate that the app keeps its central promise simple. You are not opening a full banking suite with investing tools, complicated charts, or a long list of unrelated financial products. The focus is early access to earned wages. That narrow purpose helps a first-time user understand what the app is for, although it also means you should not expect it to manage your entire financial life.
A useful way to approach the service is to decide the exact reason for using it before opening the application. If the need is a one-off timing issue and you already know when your normal pay will arrive, the decision is easier. If you are considering it because your regular income cannot cover recurring expenses, I would pause and compare the long-term effect with alternatives such as speaking to a bill provider, adjusting a due date, or using an existing emergency fund.
How I would handle the first setup
After installing the app, I would begin with the basic account and eligibility flow rather than trying to guess how much money might be available. Have your employment and pay information ready, and use details that match your official records. Small inconsistencies in names, employment information, or account details can turn a simple setup into a review process, especially in a finance app where access to earned pay must be tied to the right person.
Other Stories to Read




The most reassuring approach is to read each connection or verification screen before approving it. A first-time user may be tempted to tap through quickly because the promise sounds straightforward, but this is exactly where you should understand what information is being requested and why. If the app asks you to connect payroll or employment details, check that the selected employer and pay information are correct before continuing.
I would also set aside a few minutes when you are not already dealing with an urgent bill. Rushing through setup while stressed makes it easier to miss a mismatch or misunderstand the timing of an advance. The app may be free to download, but your time still has value, and a careful first setup gives you a better chance of knowing whether it is useful before an emergency arrives.
One practical tip is to keep your normal payday visible while you complete the process. Early access only helps if you understand how it relates to the next regular payment. Think of the app as moving part of your pay forward, not creating extra income. That mental model prevents a common mistake: treating the available amount as new spending power and forgetting that the next paycheck may arrive with less room in it.
Turning the first approval into a meaningful result
The first successful action should be modest. If the app shows that you can access earned pay, I would request only what solves the immediate problem instead of taking the maximum amount simply because it is offered. This is one of the most useful habits with any early-pay service: match the request to a specific expense, then stop. It keeps the feature from becoming an automatic extension of your everyday spending.
Imagine that your car needs fuel to get to work, but your paycheck is several days away. In that situation, early access can have a clear purpose and a measurable benefit: you can cover the necessary trip, continue working, and wait for the normal payroll cycle. By contrast, using the same tool for restaurant meals, impulse purchases, and routine shopping can create a pattern where every payday is partly committed before it arrives.
Before confirming a request, I would review the amount, the destination of the funds, and the expected timing. Even when a service is designed to be simple, financial transfers are not something I like to treat casually. If the money is needed for a bill, check whether the transfer timing actually fits the bill’s deadline. “Early” is useful only when it arrives early enough for the real-world payment you are trying to make.
Another non-obvious advantage of starting small is that it lets you judge the workflow without putting your whole pay cycle under pressure. You can see how clearly the app explains the request, how comfortable you are with the timing, and whether the process fits your routine. A successful first use is not merely receiving money; it is understanding exactly what happens before and after that transaction.
Once the immediate need is handled, record the amount and the date in your own budget. I would not rely on memory, particularly if I use the service more than once. A simple note showing what was accessed and which upcoming paycheck it affects can reveal whether the app is helping with occasional timing gaps or quietly becoming part of a recurring shortfall.
Where first-time users may get confused
The phrase “earned pay” is the key to understanding the product. It does not mean every user can request any amount at any time. Access depends on the relationship between your work, payroll information, and the amount already earned. If the app does not show the amount you expected, that does not automatically mean something is broken; it may reflect how current earnings are being recognized or whether the setup has finished.
Another possible source of confusion is the difference between being eligible and receiving funds immediately. A user may complete the initial steps and assume the money must appear at once, but financial transfers can involve timing considerations. I would read the confirmation screen carefully and avoid promising a payment deadline to someone else until the app clearly shows that the transfer has been completed.
The no-loan, no-interest positioning can also lead people to overlook the budget impact. Even if the service does not charge interest, the next regular paycheck still has to account for the pay that was accessed early. That is the central trade-off. The cost may not be an interest charge, but the timing of your income changes, and that can matter just as much to someone whose budget is already tight.
I would also avoid assuming that the app can solve every kind of emergency. If you need a large amount for rent, medical care, debt consolidation, or a long-term financial problem, early wage access may be too limited or too temporary. In those cases, a conversation with the bill provider, an employer, a credit counselor, or a trusted financial institution may be more appropriate than repeatedly moving wages forward.
Privacy and account security deserve ordinary caution as well. Use a device you control, protect your account credentials, and review every screen involving employment or payment information. These are not dramatic steps, but they are sensible whenever an app handles personal financial details. I would rather spend an extra minute checking a connection than discover later that the wrong account or employer information was used.
How it compares with familiar alternatives
Compared with a credit card cash advance, this app’s appeal is its focus on earned wages rather than borrowing against a credit limit. A credit card may be more flexible for a larger purchase or a merchant that does not accept the app’s transfer route, but cash advances can carry interest and other costs. For a short gap between completed work and payday, accessing earned pay can feel more directly connected to the problem.
Compared with a traditional payday loan, the difference is even more important. A payday loan is built around borrowing and repayment, while this service is presented as early access to money you have already earned. That does not make it automatically right for every situation, but it can be a less complicated concept for someone who needs to manage timing rather than take on a new high-cost debt obligation.
Compared with an employer payroll advance, Get Paid Early: Cash Advance may be more convenient for users who prefer handling the request through an app. An employer may be the better route when you need a larger exception, want to discuss a recurring issue, or need a human explanation of payroll timing. The app is strongest when the need is specific and the normal pay information can be matched without much trouble.
Compared with simply waiting for payday, the app offers flexibility but reduces the cushion in the next pay cycle. Waiting is the better option when the expense can safely be delayed and you want to preserve the full paycheck. Early access is more defensible when delaying the expense would cause a concrete problem, such as missing work or falling behind on an essential bill.
Who will benefit, and who should skip it
I see the best fit as someone with a regular earned-income pattern who occasionally faces a mismatch between when work is completed and when money becomes available. That person can name the expense, understands the next payday, and can avoid requesting more than necessary. For them, the app may be a practical buffer rather than a permanent financial habit.
It may also suit a first-time user who wants a focused finance tool instead of a broad banking application. The free price removes an obvious barrier to trying the service, and the Everyone rating makes the product feel accessible at the store level. Even so, accessibility should not be confused with guaranteed suitability: the real question is whether early access improves the user’s cash flow or merely postpones the same problem.
I would skip it if your income is unpredictable, your payroll details are changing, or you cannot confidently track how an early request affects the next paycheck. I would also avoid making it a routine solution for groceries, subscriptions, or ordinary spending. When the same gap appears every pay cycle, the better answer is usually a broader budget change, a different due date, additional income, or professional guidance.
My next-step advice after trying it
After the first use, I would wait until the next normal pay cycle and compare what I expected with what actually happened. Did the early access solve the intended expense? Was the remaining paycheck enough for scheduled bills? Did the timing make sense? Those answers are more valuable than simply deciding whether the app worked once.
If the experience was clear and the request covered a genuine short-term need, keep the app as an occasional option rather than an automatic payday ritual. Save a note about the workflow and the amount that felt manageable. If the experience made your next paycheck noticeably harder to handle, that is a strong signal to stop using early access and look for a solution that changes the underlying budget.
My overall view is positive but careful. StreamFunds, Inc. has made a focused finance app for a real everyday problem, and the promise of accessing earned pay without loans or interest is easier to understand than many borrowing alternatives. The strongest result comes from using it deliberately: verify your details, request only what you need, confirm the timing, and account for the effect on your next paycheck.
For someone facing an occasional payday gap, I would consider giving it a try. For someone already relying on advances to reach the end of every pay period, I would recommend stepping back before installing it. The app is most useful as a controlled timing tool, not as a substitute for income or a complete financial plan.
Highlights
- Fast access to part of your earned wages before payday.
- Simple application process with minimal paperwork required.
- No traditional credit check for many advance requests.
- Repayment is usually automatic on your next scheduled payday.
- Useful budgeting tools can help track income and upcoming bills.
Limitations
- Advance limits may be low for new or occasional users.
- Optional express-transfer fees can reduce the amount you receive.
- Requires verified employment and regular paycheck deposits.
- Eligibility and availability may vary by employer or location.
- Late or failed payroll deposits could affect repayment and account access.
Frequently Asked Questions
01What is Get Paid Early: Cash Advance?
Get Paid Early: Cash Advance is a financial app designed to help eligible users access part of their expected income before their regular payday. After signing up and connecting the required information, the app may display available advance options, repayment details, and any applicable fees. Availability, limits, and services can vary depending on your location, employer, income information, and account history.
02How does the cash advance process work?
After creating an account, you generally need to provide personal and financial information and complete any required verification steps. If you qualify, the app shows the amount you may be able to receive and explains how repayment works. Funds may arrive quickly, but delivery times depend on the selected transfer method, your bank, weekends, holidays, and the provider’s approval process.
03Are there fees or other costs to use the app?
A cash advance is not necessarily free, so users should carefully review the complete cost before accepting an offer. Depending on the service and transaction method, charges may include subscription fees, express-transfer fees, optional tips, or other disclosed costs. Read the repayment summary and terms inside the app, and avoid accepting an advance unless you understand exactly what you will owe.
04What information and permissions does Get Paid Early: Cash Advance require?
The app may request details such as your name, contact information, employment or income data, bank account information, and identity verification documents. It may also ask for permissions needed to connect financial accounts or confirm eligibility. Before continuing, review the privacy policy and permission requests carefully. Only provide information through the official app and download it from a trusted store.
05What should I know about repayment and eligibility before downloading?
Eligibility is not guaranteed, and approval may depend on factors such as income, employment, banking activity, location, account history, and successful identity checks. Repayment is typically scheduled for a future date, often around your next payday, and the amount may be withdrawn automatically from a linked account. Make sure the repayment will fit your budget, because a failed payment could lead to additional problems or bank charges.


